

Cashli: Cash Advance & Rewards
by Cashli Funds
4.1
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.1
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
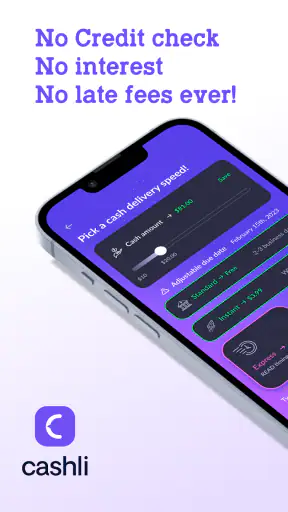
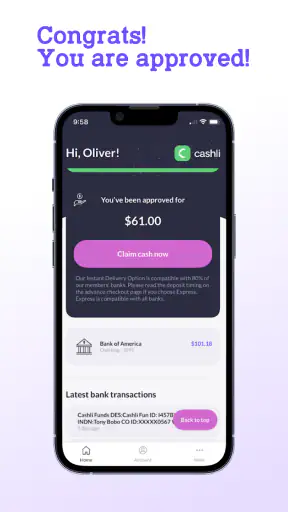
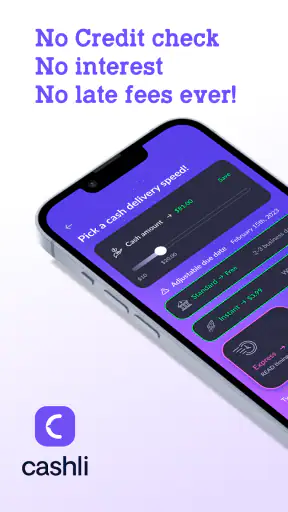
 Analysis by Getfullapps
When money gets tight between paydays, the appeal of Cashli: Cash Advance & Rewards is easy to understand. It is a free finance app from Cashli Funds that presents itself as a way to request a small amount of extra cash and engage with rewards in the same place. I approached it less like a promise of effortless money and more like a tool that deserves careful checking before you connect personal financial information.
My overall impression is cautious rather than dismissive. The app has a clear everyday use case, especially for someone facing a short-lived expense, but a cash-advance product should never be judged only by how quickly it appears to solve a problem. The important questions are practical: what information does the app request, what choices are visible during setup, how clearly are repayment obligations explained, and can I control or stop the account without confusion?
Cashli is listed in the Finance category, carries an Everyone age rating, and has reached over 100 thousand installs. Its average rating is 4.1 from around 4.9 thousand ratings, with roughly 2.8 thousand written reviews. Those figures suggest that many people have tried it, but popularity is not a substitute for reading every screen before accepting an advance. I would treat the rating as a reason to investigate, not as proof that the service fits my situation.
What using Cashli feels like when trust matters
The first thing I would keep in mind is that this is not simply a budgeting calculator or a coupon app. The store summary focuses on getting up to 150 dollars, so the central experience is connected to accessing money rather than merely tracking spending. That distinction changes how I would use it: I would open the app for a specific, manageable need, not browse it casually or rely on it as a permanent income source.
In a realistic situation, imagine that my phone bill is due before payday and I know the next deposit will cover the gap. I might consider Cashli for that one-off timing problem, but I would first write down the amount I need, the date I can repay it, and the total cost shown in the app. If the final screen makes any part of that unclear, I would stop rather than tap through simply because the need feels urgent.
That habit is especially important with financial apps. A fast application can feel reassuring while encouraging rushed decisions. I prefer to slow down at the points where Cashli asks for identity, bank, employment, or repayment-related information. A trustworthy experience is not only about getting an answer quickly; it is also about giving me enough context to understand what I am agreeing to.
The developer is Cashli Funds, and the current version is 1.0.19. The app supports Android 8.0 and later, which makes it accessible to many older devices as well as newer phones. I would still keep the operating system updated and install the app only from the official store route, because financial information deserves more care than an ordinary entertainment download.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What I would check before requesting money
I would begin by reading the full advance details rather than focusing on the headline amount. “Up to” is not the same as a guaranteed amount, and the amount offered to one person may not be the amount offered to another. Before accepting anything, I would look for the repayment date, any fee or charge, the total amount to be repaid, and the method used to collect it.
I would also check whether the app lets me review the agreement before the request becomes final. A useful workflow should give me a clear moment to cancel, go back, or decline. If the interface moves directly from a cheerful offer to an irreversible confirmation without a readable summary, that is a serious usability concern for me, regardless of how polished the rest of the app looks.
Another practical check is whether the app separates optional rewards activity from the core cash request. Rewards can be appealing, but I would not complete extra tasks, share additional information, or accept notifications merely to make the main process feel more worthwhile. I want to know which steps are necessary for the financial service and which are optional engagement features.
For me, the best approach is to take screenshots or save the confirmation details for my own records, provided the app and device allow that safely. I would record the amount requested, the expected repayment date, and the final total. This is not about distrusting every screen; it is about avoiding a memory-based dispute when a financial transaction has several stages.
Account controls are more important than a smooth first screen
A finance app earns my confidence through visible controls. I want to know how to change contact information, review linked accounts, manage notifications, and close the account. I would look for these options in the profile or settings area before requesting money, not after a problem appears.
I would also check whether the app clearly identifies permissions during installation and use. I do not assume that a finance app needs access to everything on my phone. If a permission seems unrelated to requesting an advance or managing rewards, I would deny it and see whether the essential service still works. If refusing an optional permission blocks the entire experience, I would reconsider whether the convenience is worth the trade-off.
Notifications deserve special attention. A reminder about repayment may be useful, while repeated promotional alerts can become distracting. I would keep essential account notices enabled but turn off marketing notifications if the controls allow it. A good account experience should let me distinguish between information I need and messages designed to bring me back into the app.
The same principle applies to linked financial accounts. I would verify which account is being used, why it is needed, and how to remove it later. I would not connect a secondary account simply to experiment, because adding more financial relationships creates more opportunities for confusion. If I could not identify the connected account or find a removal path, I would not proceed.
Data-sensitive moments deserve a pause
The most sensitive part of using Cashli is not browsing the interface; it is entering information that can affect eligibility, identity verification, or repayment. I would read each request carefully and avoid typing information into fields that do not explain their purpose. If the app asks me to move from its screen to another service, I would check the name and destination before continuing.
I would never share a verification code with another person, even if a message or call appeared to come from a financial service. I would also avoid using public Wi-Fi for account setup or repayment changes. These are simple precautions, but they matter more when an app is connected to money than when I am signing up for a casual game.
Privacy choices should be treated as part of the product experience, not as paperwork to ignore. I would read the privacy information and look for explanations of what is collected, why it is collected, how it is used, and whether information is shared with service providers. I would pay particular attention to choices around marketing, personalization, and rewards participation.
I would not assume that a free download means the service has no financial consequences. The app price is free, but a cash advance can still involve terms that matter. Before accepting an offer, I would focus on the transaction details rather than the absence of a download charge. Those are separate questions, and confusing them is an easy way to make a rushed decision.
Rewards should remain optional in my decision
The rewards angle gives Cashli a different feel from a conventional short-term lending tool. It may make the app more engaging, but engagement is not the same as value. I would evaluate rewards by asking whether they genuinely reduce my costs or simply encourage more time, more permissions, or more personal information.
My rule would be simple: decide whether the advance is suitable without counting uncertain rewards. If the repayment works only because I expect to earn something later, I would not accept it. Rewards can change, take time, or depend on conditions, while a repayment obligation remains a fixed responsibility.
I would also separate financial urgency from reward hunting. Someone who needs help paying for groceries should not feel pressured to complete unrelated activities before understanding the advance terms. The app is more useful when rewards are an optional extra rather than a distraction from the central financial decision.
A less obvious trade-off is attention. Every additional offer, notification, or reward prompt can make it harder to notice a repayment reminder or account message. I would periodically review the app’s notification settings and keep the home screen focused on information I actually need. That small adjustment can make the experience less noisy and reduce the risk of overlooking an important date.
Where Cashli fits better than usual alternatives
Compared with a traditional budgeting app, Cashli is aimed at immediate access and rewards rather than long-term spending analysis. If my real problem is that I regularly run out of money, a budget, emergency fund, or conversation with my bank may help more than another advance. Borrowing can solve timing; it does not solve a recurring gap between income and expenses.
Compared with a credit card, the app may feel more focused on a single short-term need, while a card can remain available for repeated spending. That convenience can become a weakness if I start using either option automatically. I would compare the total cost, repayment flexibility, and consequences of missing a payment rather than choosing based on speed alone.
Compared with asking a friend or family member, Cashli may feel more private and structured, but it also places the decision inside a formal financial process. A personal arrangement may be more flexible, while an app may offer clearer digital records. Neither option is automatically better; the right choice depends on whether I can repay comfortably and whether I understand the terms.
For someone who only wants rewards, a dedicated rewards app may be a better fit if it offers clearer earning rules and does not require a cash advance. For someone who needs detailed financial planning, a banking app or budgeting service may provide a broader view of income, bills, and savings. Cashli makes the most sense when the immediate use case is specific and the user is willing to inspect the financial and privacy choices closely.
Who should use it and who should step away
I can see Cashli working for an adult who has a temporary cash-flow problem, knows exactly how much is needed, and has a dependable repayment plan. That person should be comfortable reviewing terms, managing permissions, and checking account controls before linking financial information. The free availability and broad Android compatibility make trying the app straightforward, but the decision to request money should remain deliberate.
I would avoid it if I am already behind on several bills, using one advance to repay another, or unsure when my next reliable income will arrive. In those situations, a short-term advance can postpone the problem and add another date to manage. I would first look for help from a bank, a nonprofit financial counselor, a utility provider, or another trusted local resource.
I would also skip the app if the privacy choices are difficult to understand, if the requested permissions feel excessive, or if I cannot find a clear way to manage or close the account. A financial product should not require me to ignore basic questions about control. Convenience matters, but control matters more.
Parents should remember that an Everyone rating describes the store’s content classification, not financial suitability for every person. I would not let a young or inexperienced user request money without adult guidance and a clear understanding of repayment. The age label does not remove the need for responsible financial judgment.
My cautious verdict after weighing the trade-offs
Cashli: Cash Advance & Rewards is interesting because it combines a short-term cash request with a rewards-oriented experience, but that combination should not blur the difference between optional engagement and a real financial obligation. I like the possibility of using it for a clearly defined timing problem, and I appreciate that the app is free to install and available on older Android versions.
At the same time, I would not recommend opening it with the mindset that it is effortless money. I would treat every request for identity, account access, permissions, and repayment authorization as a decision point. I would read the final offer, save the important details, turn off unnecessary notifications, and avoid relying on rewards to make the numbers work.
The app’s 4.1 average and substantial user base make it worth examining, but they do not answer the personal questions that matter most: can I repay on time, do I understand the full cost, and am I comfortable with the information I am sharing? My recommendation is therefore conditional. Use Cashli only for a manageable, well-understood short-term need, and keep control of every permission and repayment choice.
If I had a stable repayment date and a small, specific expense, I would consider testing the experience carefully. If my finances were already unstable or the app’s choices were unclear, I would choose a non-borrowing alternative instead. That cautious boundary is what makes the app more useful: it keeps a convenient tool from becoming an automatic answer to a problem that needs a larger solution.
Pros
- Fast application process with clear eligibility information
- No traditional credit check may help users with limited credit history
- Flexible repayment options can fit different payday schedules
- Rewards provide extra value for completing eligible activities
- Simple interface makes advances and repayments easy to track
Cons
- Advance limits may be low for larger emergency expenses
- Fees or expedited-transfer charges can reduce the amount received
- Repayment is usually tied to your next paycheck
- Eligibility and available features may vary by state
- Some rewards may require substantial time or activity to redeem
FAQs for Cashli: Cash Advance & Rewards
What is Cashli: Cash Advance & Rewards, and how does it work?
Cashli: Cash Advance & Rewards is a financial app that may help eligible users access cash advances and earn rewards through selected activities or offers. After installing it, you generally create an account, provide the requested personal and financial information, and review the advance terms available to you. Approval, advance limits, fees, repayment dates, and reward availability can vary by user, location, and current app policies.
Is Cashli: Cash Advance & Rewards a legitimate and safe app to use?
Before using Cashli, download it only from the official Google Play Store or Apple App Store and check the publisher name, ratings, privacy policy, and recent user reviews. As with any financial service, the app may request sensitive information, so review its permissions and data practices carefully. Use a strong password, avoid sharing login codes, and contact official support if you notice suspicious activity or unexpected charges.
How much money can I receive through Cashli, and what does it cost?
The amount available through Cashli is not necessarily the same for every user. It may depend on factors such as account history, eligibility checks, location, income information, and repayment behavior. Carefully examine the offer screen before accepting an advance, including any service fees, optional charges, repayment amount, and due date. Never assume that a displayed maximum is guaranteed or that an advance is free.
How do repayment and eligibility work in Cashli?
Eligibility and repayment requirements are determined by Cashli’s current terms and your individual profile. You may need to provide identity, employment, banking, or other financial details, and the app could use this information to assess available features. If you accept an advance, repayment may be scheduled automatically or require manual action, depending on the agreement. Read every disclosure and make sure the due date fits your budget.
Can I earn rewards with Cashli, and can I use the app on Android or iPhone?
Cashli may offer rewards for completing activities, participating in promotions, or using selected partner services, but the rules, reward values, and redemption options can change. Some offers may include eligibility restrictions or additional terms, so read the conditions before participating. The app’s availability and supported features can also differ between Android and iOS, as well as by country or region, so confirm compatibility in the official store listing.

Cashli: Cash Advance & Rewards
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@cashli.io, visit https://www.cashli.io, or review their https://www.cashli.io/privacy-policy-english.










